The chip selloff that began in Asia reached Wall Street on Monday and dragged every major index with it. A day before Nvidia reports without Jensen Huang, investors chose to sell first and wait for answers later.
MoneyTurkey | Markets wrap | 16 November 2026, US close
Key points
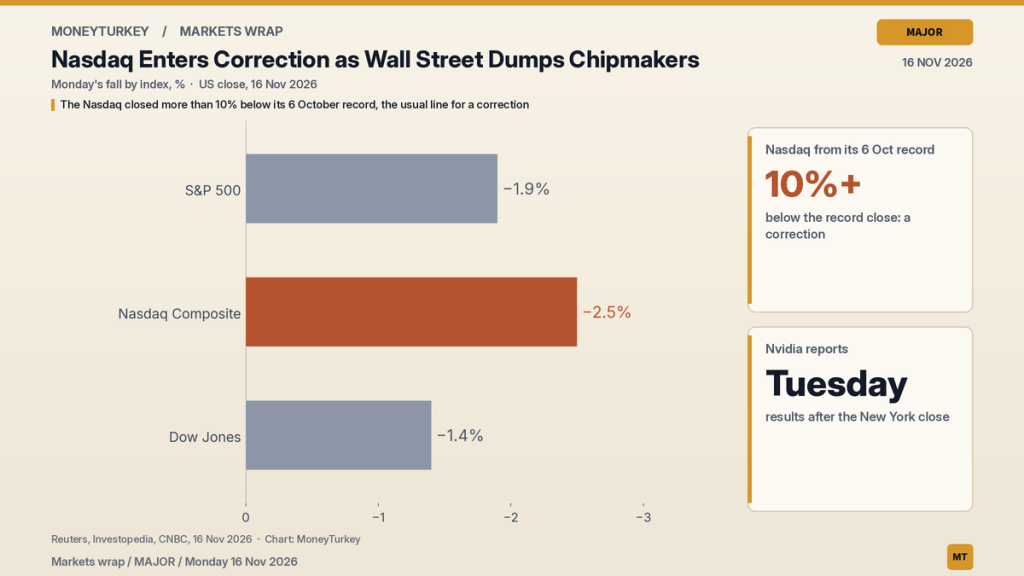
- The S&P 500 fell 1.9%, the Nasdaq Composite about 2.5% and the Dow Jones Industrial Average about 1.4%, according to Reuters and AP
- The Nasdaq ended more than 10% below its 6 October record close, which puts it in a correction
- The Philadelphia Semiconductor Index lost more than 4% and Nvidia more than 4%, the day before its first results since Huang resigned
- Fed Chair Kevin Warsh’s speech on AI gave no hint on rates, and markets still price a December rate rise as all but certain
What happened
The selling built through the session. The S&P 500 lost 1.89% to 7,418.41, its third straight fall, according to Reuters’ preliminary close and AP, which put the drop at 1.9%. The Nasdaq Composite fell about 2.5%, to 24,516.11 on Reuters’ preliminary data, and AP also had it down 2.5%. The Dow fell more than 700 points, or about 1.4%, to around 51,600, Reuters and CNBC reported.
It was a sharp turn from last week, when all three indexes posted their best week since early August, with the S&P 500 up 2.5% and the Nasdaq up 2.3%, according to Investopedia and Investing.com. Losers outnumbered winners by more than three to one on the New York Stock Exchange, Reuters said. Consumer staples were the only S&P 500 sector to rise, Investopedia and CNBC reported.
The Nasdaq closed more than 10% below its record close of 6 October, the usual definition of a correction, Reuters reported. Investopedia had the index 9% below that peak before Monday’s fall.
Chipmakers led the way down
The Philadelphia Semiconductor Index dropped more than 4%, according to Reuters and Oninvest. Micron and Intel each lost more than 6%, and CoreWeave, which rents out Nvidia chips through the cloud, fell about 6%, the same two sources reported.
Nvidia fell more than 4%, after a 13% slide last week, Investopedia and CNBC reported. Its market value had already dropped to $3.9 trillion by Friday from about $5.8 trillion in early October, according to LSEG data cited by Reuters and Investing.com. A source told CNBC that the board is not discussing bringing Huang back as chief executive, and Oninvest, citing CNBC and the Financial Times, reported the same. Treasury Secretary Scott Bessent said over the weekend that the company needs “a dramatic shake-up”, Benzinga and CNBC reported.
Washington added to the pressure. The Commerce Department issued a rule on Monday requiring licences to ship advanced AI chips to Indonesia, Malaysia, Singapore, Thailand and Brazil, to stop Chinese companies reaching them through data centres abroad, Benzinga and Yahoo Finance reported.
Rates and the dollar gave no relief
Warsh spoke in San Francisco on AI and productivity and said nothing about the path of interest rates, according to the Federal Reserve’s published text and AP. He did set out a downside case: “SI could disappoint,” he said, using his term for super intelligence, and after heavy investment and stock market gains “equity valuations could fall, leading to an economic slowdown.”
His remarks did not change bets on the Fed. Markets price a better than 90% chance of a quarter-point rise at the 9 December meeting, on CME FedWatch data reported by Reuters and FXStreet. The dollar stayed near its strongest level in about 19 months, Reuters and FXStreet reported, while the 10-year Treasury yield eased to about 5.12% from 5.15% on Friday, according to Reuters and AP.
The Blindspot view
MoneyTurkey’s own Blindspot analysis, The Commoditisation of High Tech, argued on Sunday that every big technology of the past 180 years went through the same arc: capital pours in, capacity overshoots, prices collapse and most investors lose even as the technology wins. Its central warning was that the bust tends to follow the peak in capital spending, not the peak in the technology. The note named the signals to watch, and Monday touched three of them: the chip index against its June high, neocloud companies such as CoreWeave, and the IPO window. In Blindspot’s reading, a day like this is not proof that the AI cycle has turned, but it is the pattern the note told readers to watch for.
Two tests in three days
Nvidia reports fiscal third-quarter results after the New York close on Tuesday, with Colette Kress leading the call as interim chief executive, AP and Investopedia reported. Analysts expect revenue of about $109 billion, according to Reuters and Investopedia. Anthropic then expects to price its IPO on Wednesday, 18 November, and to start trading on the Nasdaq on Thursday, with 825 million shares offered at $70 to $78 each, CNBC and Yahoo Finance reported. At the top of the range the company would be valued at about $1.4 trillion, according to CNBC and Investopedia.
What to watch
- Nvidia’s results and outlook on Tuesday evening, and how Kress handles questions about leadership
- Where Anthropic prices on Wednesday, and whether demand holds after Monday’s selloff
- The Fed’s October meeting minutes on Wednesday
Related on MoneyTurkey
- The Commoditisation of High Tech
- Burry Keeps His Puts as Options Brace for a Big Nvidia Swing
- The AI Trade Lost Its Loudest Voice. Asia Blinked First.
For information only. Not investment advice.
Sources
- Reuters via StreetInsider: Wall Street ends sharply lower on AI jitters ahead of Nvidia results, Anthropic IPO
- Reuters via Financial Newsletter: Stocks fall ahead of Nvidia earnings and Anthropic IPO; oil drops
- Associated Press: Stocks tumble on Wall Street as Nvidia leads another sell-off in technology companies
- Associated Press: Fed Chairman Warsh grapples with AI’s potential economic impact, steers clear of its inflation risk
- Federal Reserve Board: Opening remarks by Chairman Warsh at the Federal Reserve’s Productivity and Jobs Task Force Conference
- CNBC via Aetos: Dow falls 700 points, Nasdaq loses 2% as Nvidia leads AI stocks lower: Live updates
- Investopedia: Stock Market Today: Major Indexes Plunge at the Start of a Big Week for the AI Trade
- Investing.com: Dow Jones, Nasdaq, S&P 500 weekly preview: Nvidia earnings, Anthropic IPO on deck
- Oninvest: The S&P 500 fell more than 2% during trading on November 16, while the Nasdaq 100 is down nearly 3%
- Benzinga: Tech Stocks Wipe Out $960 Billion as Washington Shuts China’s AI Chip Back Door in 5 Countries
- Yahoo Finance: AMD, Broadcom stocks sink on tighter US chips rules, CoreWeave drops
- FXStreet: Euro approaches 1.1000 area as Fed’s hawkishness boosts US Dollar
- CNBC: Anthropic IPO guide: The price range, date and more
- Yahoo Finance: Anthropic IPO: Claude maker to begin trading on Thursday, Nov. 19
- Investopedia: Anthropic Prices Its IPO Wednesday. Here’s What Investors Need To Know

