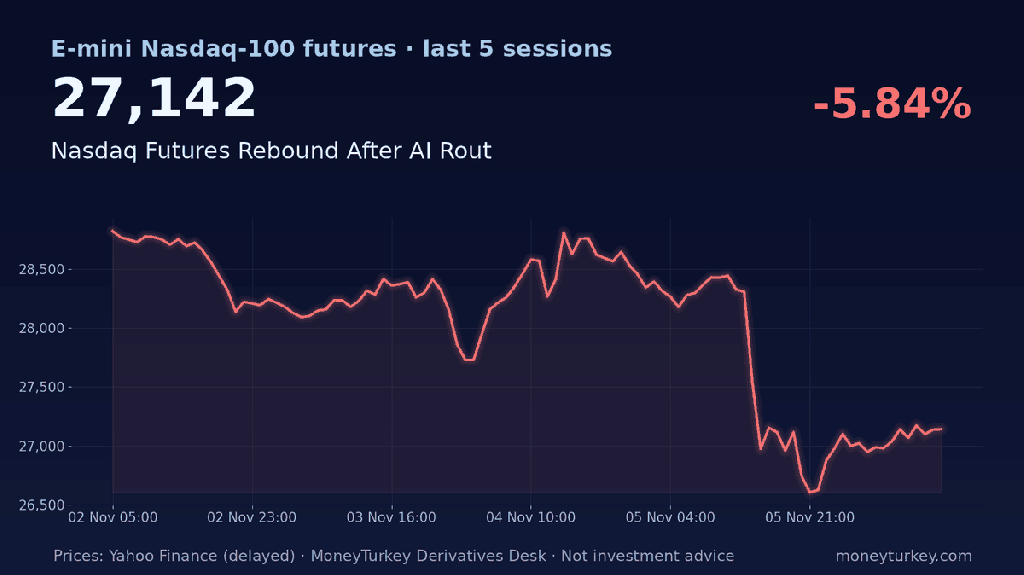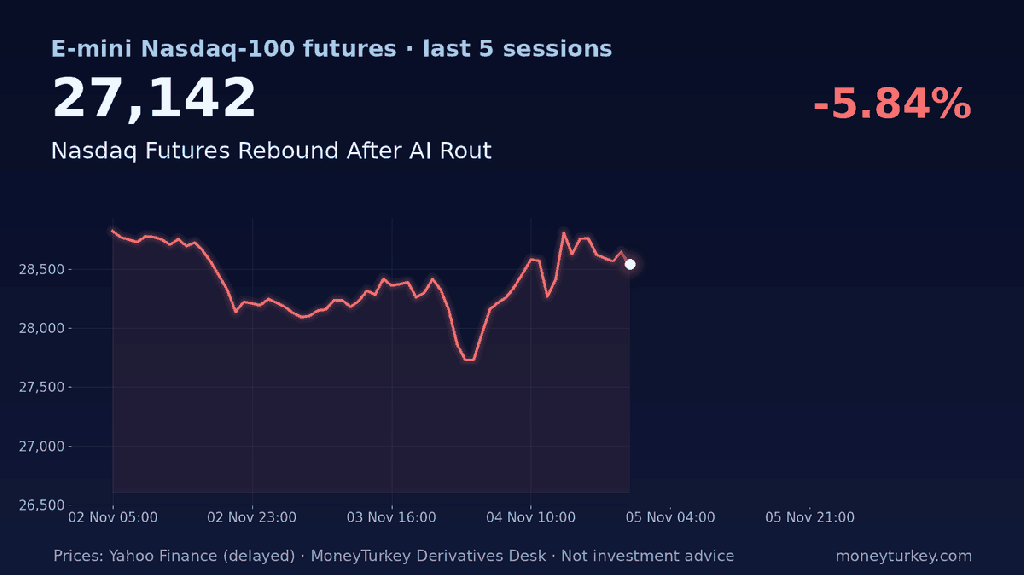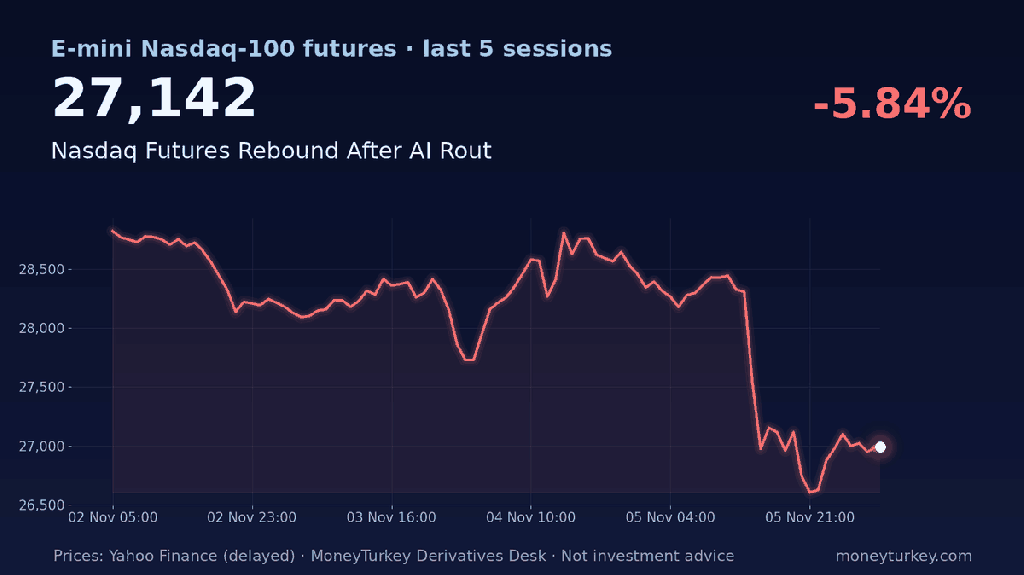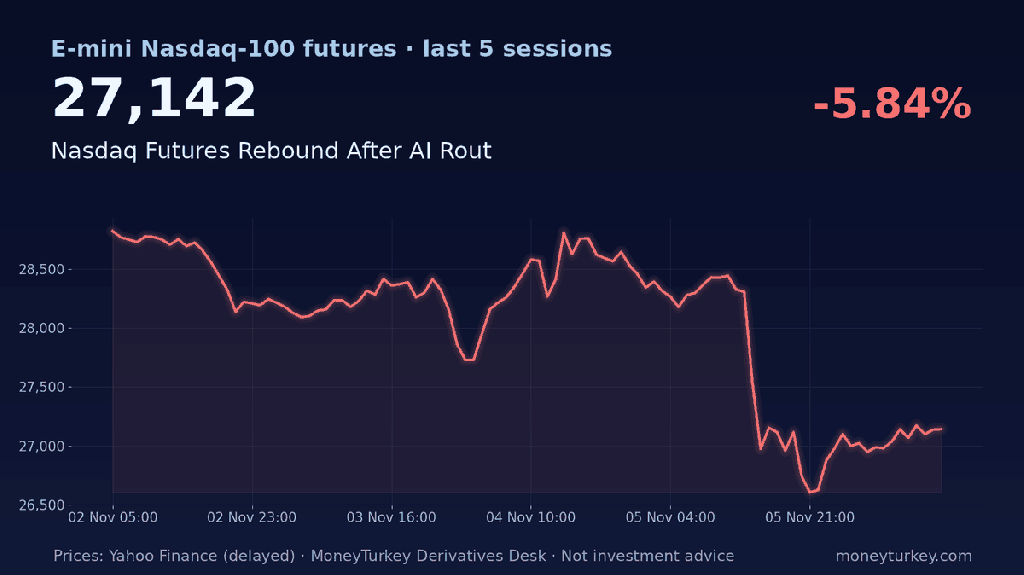
Nasdaq 100 futures were up 0.9% at 03:00 ET as the AI sell-off paused. Later on Friday, the US Bureau of Labor Statistics reported that nonfarm payrolls rose by 165,000 in October, with the unemployment rate at 4.1%.
MoneyTurkey Derivatives Desk | 6 November 2026
Key points
- Nasdaq 100 futures rose 232 points, or 0.9%, at 03:00 ET, while S&P 500 futures were flat and Dow Jones futures fell 534 points, or 1%.
- The Nasdaq Composite fell about 5.52% on Thursday, its worst day since April 2025.
Nasdaq futures recovered some ground in overnight trading after Thursday’s sharp AI-led sell-off, before the US employment report was released at 08:30 ET on Friday. The rebound came as Asian and European equity markets also posted losses. Traders had positioned ahead of data that could shape the Federal Reserve’s next rate decision.
What happened
US stock index futures opened mixed on Friday after the Nasdaq Composite fell about 5.52% on Thursday, its worst day since April 2025, as semiconductor makers, data-centre developers and electricity providers led the fall. Tesla and SpaceX shares also posted substantial losses, according to market reports.
The sell-off followed Democratic Party gains in the US midterm elections. Investors reassessed the outlook for artificial-intelligence spending as political risk around data-centre build-outs and energy demand rose in focus. The S&P 500 fell 4.36% and the Dow Jones Industrial Average dropped 3.44% on Thursday.
Asian markets extended the decline. The MSCI Asia Pacific index recorded its largest drop since 2025, Taiwan’s benchmark entered bear-market territory, and heavy selling in South Korea — including chipmakers SK Hynix and Samsung Electronics — triggered a market circuit breaker. European equities opened lower, with the STOXX 600 pressured by technology shares.
What the futures and options market is pricing
At 03:00 ET, Nasdaq 100 futures traded up 232 points, or 0.9%, signalling a partial recovery in technology shares. S&P 500 futures were unchanged and Dow Jones futures fell 534 points, or 1%. The moves, recorded before the 08:30 ET jobs release, pointed to a divergence between financial and technology sectors.
A widely followed volatility indicator posted its largest daily rise since April 2025, reflecting the sharp increase in market volatility. Traders in equity index futures appeared to price in continued uncertainty around AI valuations after Thursday’s wipeout.
Oil prices remained volatile amid renewed attacks on vessels in the Middle East. Brent crude futures gained almost 4% on Thursday and US West Texas Intermediate rose 2.7%, according to market reports, after earlier midweek losses.
Why it matters
The US Bureau of Labor Statistics reported at 08:30 ET that total nonfarm payroll employment rose by 165,000 in October, while the unemployment rate changed little at 4.1%. Market reports ahead of the release had put the economist consensus near 62,000–65,000 new October jobs, with the unemployment rate seen steady at 4.2%, so payrolls came in well above that pre-release consensus.
The sharp reversal in AI-related stocks has raised questions about the sustainability of current valuations. Market participants are watching whether the rebound in Nasdaq futures can hold or whether further selling pressure returns after the data release.
The mixed futures picture also highlights sector rotation. Financial stocks such as Goldman Sachs, JPMorgan Chase and American Express advanced in premarket trading, supporting Dow-linked futures while technology names remained under pressure.
What to watch
- US non-farm payrolls rose by 165,000 in October and unemployment was 4.1%, according to the Bureau of Labor Statistics (released 08:30 ET)
- Response in Nasdaq 100 and S&P 500 futures post-release
- Follow-through in equity-index and VIX futures after Thursday’s spike
- Whether the Nasdaq futures rebound holds into the cash session
Related on MoneyTurkey
For information only. Not investment advice.
Sources
- Yahoo Finance: https://finance.yahoo.com/markets/stocks/articles/us-stock-futures-mixed-ai-101925836.html
- Yahoo Finance: https://uk.finance.yahoo.com/news/wall-street-futures-diverge-dow-141731818.html
- WSJ: https://www.wsj.com/finance/stocks/nasdaq-futures-steady-after-asian-ai-rout-as-investors-brace-for-jobs-day-83415c52
- CNBC: https://www.cnbc.com/video/2026/11/06/nasdaq-futures-rebound-after-worst-rout-in-19-months-as-ai-stocks-bounce.html
- US Bureau of Labor Statistics: https://www.bls.gov/news.release/empsit.htm

