By MoneyTurkey editors | Andrew’s Corner | 5 November 2026, London
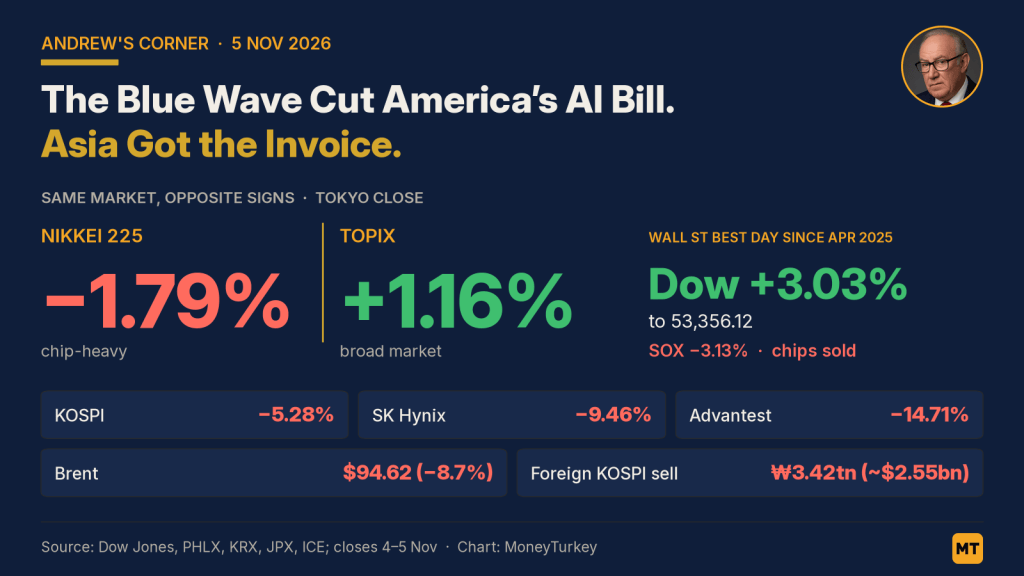
Wall Street threw a party on Wednesday. The Dow rose 1,569 points, or 3.03%, to 53,356.12, its best day since April 2025. The S&P 500 added 1.58%. Read only those numbers and the Democratic sweep looks like a relief rally. Read Seoul’s close on Thursday and it looks like a rout: the KOSPI fell 5.28% to 5,383.80, its lowest close since April, with sell-side sidecars tripped on both the main board and the Kosdaq.
Both are true. They are the same trade, seen from opposite ends of one invoice.
Buyers saved, sellers paid
Here is the mechanism. A Democratic Congress, plus Democratic wins in data-centre states such as Texas, where governor-elect Gina Hinojosa has pledged a moratorium, raises the odds that America’s AI buildout slows. A slower buildout is a cost for the companies that sell the hardware and a saving for the companies that buy it.
New York priced the saving. Microsoft and Amazon rose more than 6% on Wednesday and Apple 5.31%, as investors read less capital spending as more free cash flow. The sellers took the hit: the Philadelphia Semiconductor Index fell 3.13%, Micron 7% and CoreWeave 9.9%.
Asia makes the hardware, so Asia got the bill. On Thursday Advantest fell 14.71% and Tokyo Electron 9.42%. SK Hynix lost 9.46% to ₩1,264,000 (~$942), dragging its market value below ₩1,000 trillion to ₩923 trillion (~$688 billion). Samsung Electronics fell 7.57% and briefly traded below ₩200,000 (~$149) for the first time since July. Foreign investors sold a net ₩3.42 trillion (~$2.55 billion) of KOSPI shares, their fifth straight day of selling. Taiwan’s main index fell 3.2%.
The headline indices overstate it
This is the part most London and New York books will skip. Tokyo is the clearest case. The Nikkei 225 fell 1.79% because it is price-weighted and heavy in Advantest and SoftBank Group. The broader TOPIX rose 1.16%, and gainers beat losers on the Prime market by 1,130 to 410. Japan as a whole had a decent day; its chip-equipment makers had a terrible one.
Seoul tells the same story in smaller type. Hyundai Motor rose 3.53% and Kia 5.22% on hopes that a weaker White House means softer tariffs, while drugmakers and IT services rallied. And while foreigners dumped cash shares, they were net buyers of about ₩751 billion (~$560 million) of KOSPI 200 futures by mid-afternoon. That looks like hedge-and-rotate, not a stampede out of Korea.
The second invoice is oil, and it runs the other way
Gasoline was on the ballot: 59% of voters told NBC’s exit poll they were very concerned about fuel costs. Now Senate Democratic leader Chuck Schumer says the new majority can use its control of funding to end the Iran war, and Vice President JD Vance wrote that “the reason we lost is the war.” Brent settled 8.7% lower at $94.62 on Wednesday, its lowest close since 31 August.
That is a transfer from oil producers to oil importers, and importers’ markets noticed first. India’s 10-year government bond yield fell more than 11 basis points to 7.188%, its best day since early April. Indonesia’s rupiah firmed as Jakarta printed 5.47% third-quarter growth. Sterling hit its highest level since the Brexit referendum on Wednesday, going into today’s Bank of England decision.
Which invoice actually gets paid
Neither is settled. The oil leg rests on a deal that does not exist yet; an Iranian official told Reuters on Tuesday that the two sides remain far from one. The AI leg rests on a Congress that does not sit until January and on state permitting fights that take years, not weeks. Federal AI bills can still meet a veto.
My read: markets are already treating both the AI spending cut and the oil discount as done. That leaves room for disappointment on each. If it comes, Asia’s chipmakers are where it would show fastest, in both directions. A sidecar-day KOSPI with foreigners buying futures is not a market that has given up on the AI trade. It is one waiting to see the bill itemised.
What I’m watching: whether the KOSPI holds 5,200, the level Daishin Securities flags as the line where selling could accelerate; whether Brent holds near the mid-$90s or keeps sliding toward the low $90s; the Bank of England today, where a quarter-point hike is all but fully priced; and US payrolls on Friday.
The blue wave has not made America’s AI boom smaller yet. It has made the bill visible, and the bill landed in Seoul, Tokyo and Taipei first.
For information only. Not investment advice. FX conversions at about ₩1,342 per dollar.
Sources
CNBC, AP, Yonhap Infomax: US closes, Dow/S&P/Nasdaq, SOX and single stocks (4 Nov 2026)
Yonhap (Korean and English): KOSPI/Kosdaq close, sidecars, foreign flows, Samsung/SK Hynix, Hyundai/Kia, Daishin comment (5 Nov 2026)
Nikkei: Nikkei 225 and TOPIX close, Prime breadth (5 Nov 2026)
Money Today: Advantest, Tokyo Electron, Taiwan close (5 Nov 2026)
Reuters via CNA, CNBC, NBC/Yahoo Finance: Brent and WTI settlements, Vance comments, exit poll, Iran deal status (4 Nov 2026)
BBC, Scotiabank via MoneyTurkey Currencies desk: sterling, Bank of England pricing (4 Nov 2026)
MoneyTurkey desks: Indian bonds, Indonesia GDP, Asia chip open
Yesterday’s Corner: They Priced the Blue Wave. They Missed the Size.

