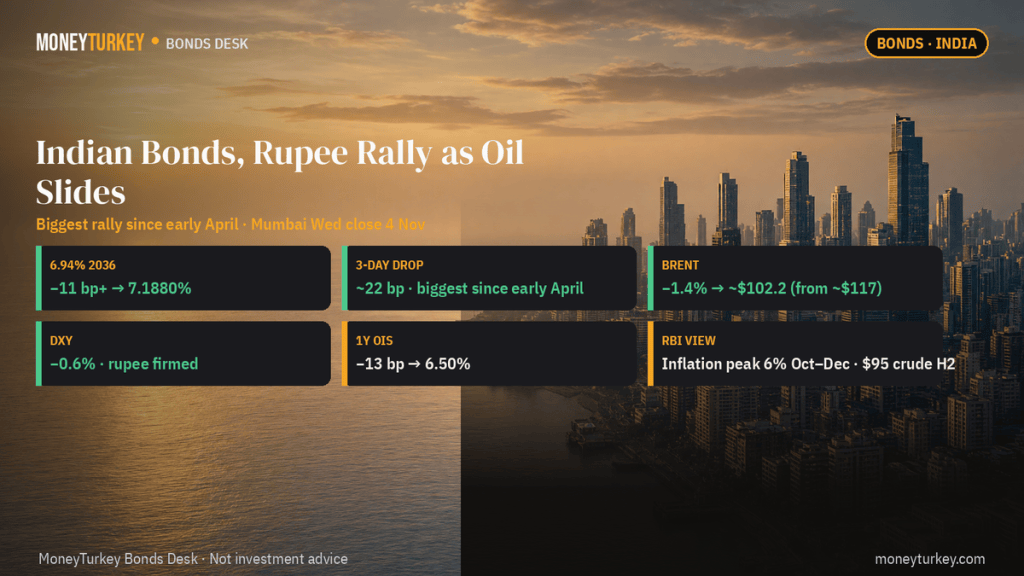
Indian government bonds posted their strongest rally since early April on Wednesday as Brent slid after the Democratic midterm sweep, cutting inflation and fiscal risk for the world’s third-largest oil importer. The benchmark 6.94% 2036 yield dropped more than 11 basis points to 7.1880%, taking its three-day fall to about 22 bp, while the rupee firmed with a softer dollar.
MoneyTurkey Bonds Desk | 5 November 2026, 07:10 London. Figures as of the Mumbai Wednesday close (4 November)
Key points
- Benchmark 6.94% 2036 G-sec yield −11 bp+ to 7.1880%; three-day drop about 22 bp — largest daily price gain since early April, Reuters via The Economic Times
- Brent −1.4% to about $102.2 a barrel on Wednesday after touching about $117 last week; dollar index −0.6% supported the rupee
- Overnight indexed swaps: 1-year OIS −13 bp to 6.50%, 2-year −17 bp to 6.47%, 5-year −14.25 bp to 6.59% as rate-hike fears cooled
Oil is still the macro trigger for Indian rates. Softening crude after the midterm verdict revived hopes of a de-escalation path in the Middle East conflict and cut the import-bill risk that had pushed yields to multi-year highs last week.
What happened
The Economic Times, citing Reuters, said Indian government bonds rallied the most since early April on Wednesday on easing oil pressures after Democrats swept the US midterms. Bond prices move inversely to yields; the three-session slide in the 2036 benchmark was the clearest local confirmation that desks were unwinding the October oil-shock premium.
Brent’s drop toward $102 eased pressure on inflation, the current account and the fiscal outlook. US 10-year Treasury yields eased about 1.5 bp alongside the dollar’s slide, giving foreign and domestic buyers room to add duration.
Policy read
The Reserve Bank of India expects inflation to peak at 6% in the October–December quarter, based on crude averaging $95 a barrel in the second half of 2026–27, after it raised the repo rate and turned its stance hawkish in October. Tata Mutual Fund said any moderation in inflation, improvement in liquidity or reduction in geopolitical risks could support bond-market performance.
Dealers still caution that the rally needs a sustained oil slide. Liquidity remains tight, the government borrowing calendar is heavy, and a renewed Middle East supply scare could reprice the curve quickly.
Why it matters
For global rates books, India’s 10-year is a clean EM oil-beta: when Brent falls and the dollar softens, local real yields and the rupee usually improve together. Wednesday’s OIS plunge shows the market is also dialling back near-term hike odds — a missed-markets tell that sits beside the US midterm tape rather than behind it.
What to watch
- Whether the 10-year can hold below 7.20% / test 7.15% if Brent stays near $100–102
- Next RBI inflation path and any liquidity measures
- FPI debt flows and Qatar-led mediation headlines that could deepen the oil slide
Related on MoneyTurkey
- ECB Holds Deposit Rate at 2.5%
- Brazil’s Treasury Cancels Auctions and Buys Back R$31.6bn After Lula’s Win
- Commodities Wrap: India Backs Lithium and Nickel Refining; US Crude Output Tops 14 Million Barrels a Day
For information only. Not investment advice.
Sources
- The Economic Times / Reuters — Indian bonds rally most since April (4 Nov 2026): economictimes.indiatimes.com
- Business Standard — Bond yields fall 11 bp, rupee gains: business-standard.com
- Bloomberg — Indian bonds, rupee rally as sliding oil eases inflation risks: bloomberg.com

