Wall Street went into midterms night with a Democratic wave as the base case. That was not the surprise. The size was.
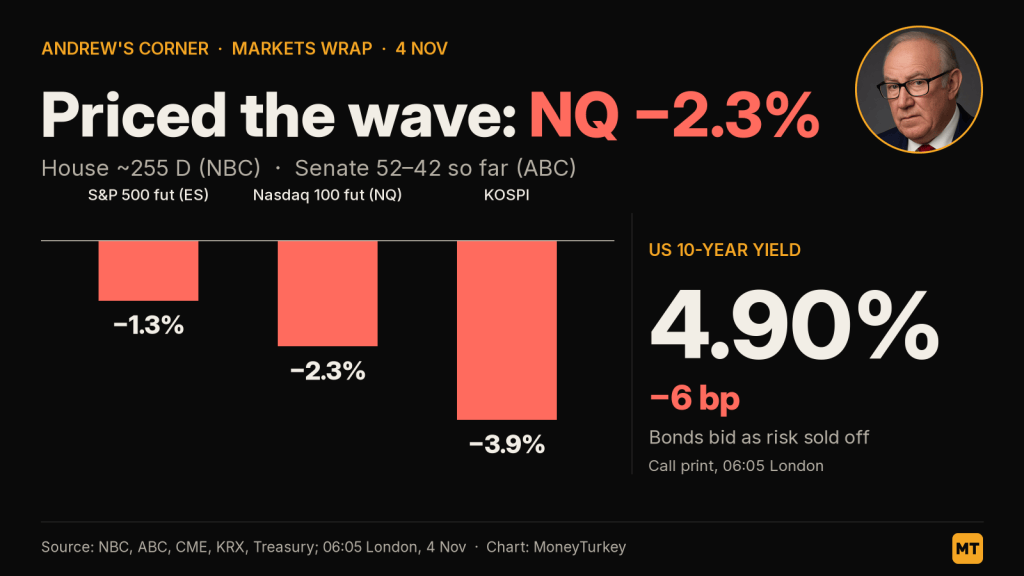
By London breakfast, Decision Desk HQ, NBC and ABC had projected Democratic control of both chambers. NBC put the House near 255 seats — potentially the largest majority in nearly two decades. ABC’s Senate count ran 52–42 with six Democratic gains already booked: Cooper’s North Carolina flip, Ossoff holding Georgia, Collins conceding Maine to Jackson, Talarico projected over Paxton in Texas, Andrews in South Carolina. Trump said he would accept the results. The red-hold tail that had been overnight optionality is finished.
The tape cared about magnitude, not direction. S&P 500 futures, up about 0.5% at the open, were down 1.3%. Nasdaq-100 futures were down 2.3%. The 10-year yield fell 6 basis points to 4.90%; the five-year tagged 4.68%. The dollar index printed 101.34 (−0.37%). This was not a shrug that “gridlock is fine.” It was a repricing of how hard a Democratic Congress can lean on AI oversight, data-centre power, and Big Tech from the chair’s gavel — even with a Republican White House that can veto bills but not rewrite every state interconnect.
Asia moved first, and that is still the piece most London and New York books treat as colour. KOSPI opened +2.43% on the “uncertainty ends” bid, then reversed as the sweep hardened — down as much as 3.9% before closing +0.62% at 5,683.80, with foreigners net sellers of ₩2.5 trillion (~$1.9 billion) (Yonhap). Battery names ripped on Democratic industry hopes: Samsung SDI +11.57%, LG Energy Solution +5.03%. Samsung Electronics slipped 0.68%. Taiwan’s TAIEX swung 1,885.72 points and closed 42,948.91 (−0.83%), TSMC from NT$2,320 (~$71) to a NT$2,235 (~$68) low and a NT$2,260 (~$69) close (−1.5%) on NT$1.11 trillion (~$33.8 billion) of turnover (CNA). The missed market was not a one-line “Asia sold chips.” It was the path — relief open, regulatory crush, partial bounce — all before New York cash.
Federal AI statutes can meet a veto. Permitting and power hookups in Texas and Georgia cannot. Those two states concentrate a large share of U.S. AI data-centre spend; if buildout slows there, Korean memory and Taiwanese foundry orders do not wait for conference committee. Treasuries bid and the dollar softened partly because a sweep also means fewer giant deficit packages. The sharper trade is the AI check: futures sold unconstrained-capex tech, while Seoul’s cash session split semiconductors from batteries. Read only the S&P future and you miss that book.
They priced the blue wave. They missed the size — and the Asian cash reaction to that size.
Sources:
- NBC / ABC / NPR–AP chamber projections and Senate calls, 4 Nov 2026
- Bloomberg / Reuters markets wraps (~05:30 London): ES, NQ, Treasuries, DXY, Asia
- Yonhap AEN20261104006851320 — KOSPI path, flows, SDI / LGES / Samsung
- CNA afe/202611040142 — TAIEX swing, TSMC
- Desk live: https://moneyturkey.com/2026/11/03/midterms-night-markets-live/

