Sterling barely moved against the dollar after the Bank of England raised Bank Rate to 4% on Thursday, with the pound holding near $1.35 (about €1.20) as markets had largely priced the quarter-point hike. The bigger currency story is the split vote and the energy-driven inflation path, which keep sterling’s rate advantage over its peers in play.
MoneyTurkey Currencies Desk | 5 November 2026, 14:25 London
Key points
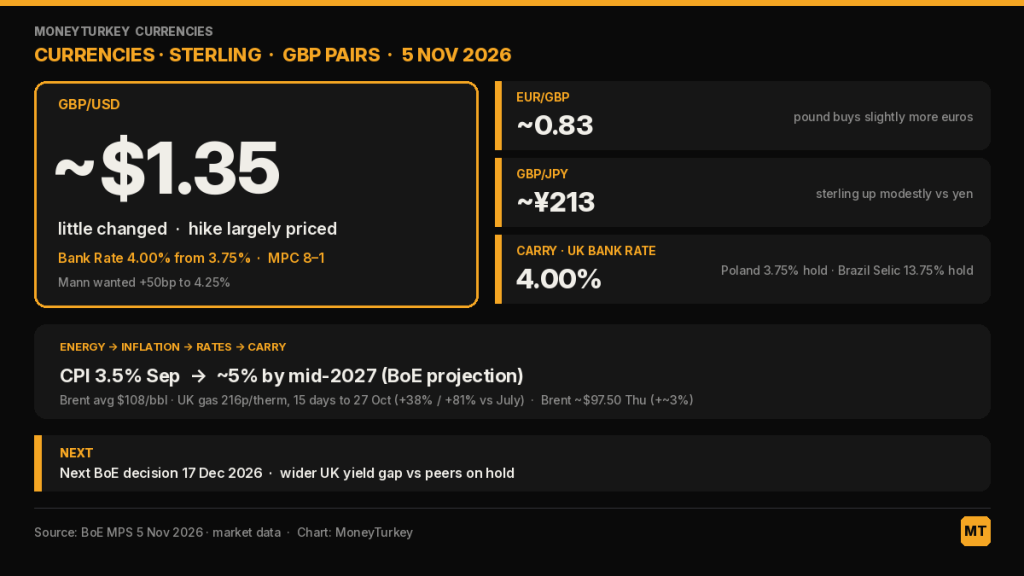
- GBP/USD was near $1.35 around 14:25 London, little changed on the day, after the MPC voted 8–1 to lift Bank Rate to 4.00% from 3.75%.
- Catherine L Mann dissented in favour of a half-point rise to 4.25%, a hawkish signal for the rate path that underpins sterling.
- Sterling firmed slightly against the euro and the yen: EUR/GBP eased to about 0.83 and GBP/JPY was near ¥213.
- UK CPI was 3.5% in September; the Bank expects around 5% by mid-2027 as energy costs feed through.
What happened in FX
The Bank published its November Monetary Policy Summary at 12:00 London. Eight members backed a 25-basis-point increase to 4%; Mann voted for 50 basis points. In the two and a half hours that followed, the pound traded in a narrow band against the dollar. GBP/USD was near $1.35 (1.3469 at 14:24 London against a 1.3472 prior close), suggesting the move was well flagged in advance.
Against other majors sterling did a little better. EUR/GBP slipped to about 0.83, meaning a pound bought slightly more euros than at Wednesday’s close, and GBP/JPY was near ¥213, up modestly on the day. MoneyTurkey’s Economics desk has the full decision, gilts and FTSE 100 reaction in its lead report on the hike.
Carry versus peers
A 4% Bank Rate widens the UK’s yield advantage over central banks that are on hold or easing. That rate gap, known as carry, tends to support a currency because holding it pays more. On Wednesday Poland’s central bank held its main rate at 3.75%, now below the UK level. Higher-yielding emerging currencies still pay more, but they carry more risk: Brazil held the Selic at 13.75% while the real stayed weak after the election.
The pound came into the decision strong. On Wednesday it hit its highest level since the Brexit vote on a trade-weighted basis as the dollar fell after the US midterms. With that much already in the price, Thursday’s hike confirmed sterling’s rate advantage rather than adding to it.
Energy, inflation and the rate path
The Bank tied the hike to energy. Front-month Brent crude averaged $108 a barrel and UK front-month natural gas 216 pence per therm over the 15 UK working days to 27 October. Those levels were 38% and 81% above where they stood at the July Monetary Policy Report, and above the July adverse-scenario assumptions. Brent was near $97.50 on Thursday afternoon, up about 3% on the day.
For currency markets, the link runs from energy to inflation to rates. Higher energy costs lift CPI. If that spreads into wages and services prices, the Bank is likely to keep tightening, which would widen sterling’s carry. The Bank said evidence of such knock-on effects is still limited, and that policy “is not on a pre-set path”. Mann’s vote for a bigger move shows at least one member wants to act sooner. Interest-rate futures moved to price further hikes after the vote.
Why it matters
If energy prices push inflation toward the Bank’s 5% path and pay growth follows, markets may price more hikes and sterling’s yield advantage could widen. If the energy shock passes through without broader spill-overs, the case for further hikes weakens and the pound’s carry support could fade. With the dollar already soft after the US vote, sterling’s next moves against the dollar may depend as much on US data as on the Bank.
What to watch
- Next UK CPI release and wage data for second-round effects
- Front-month Brent and UK natural gas futures
- Bank of England speakers, including Mann, on the next step; the next decision is due 17 December 2026
- US data and the dollar after the midterms
Related on MoneyTurkey
- Bank of England Raises Bank Rate to 4% in First Hike Since 2023
- BOE Rate Hike Bets Rise After Hawkish Vote
- Pound Hits Post-Brexit High as Dollar Slides on Democratic Midterm Sweep
- Brazil Holds Selic at 13.75% as Real Stays Weak After Lula Win
For information only. Not investment advice.
Sources
- Bank of England, Monetary Policy Summary and minutes, November 2026: bankofengland.co.uk
- Market prices: GBP/USD, EUR/GBP, GBP/JPY and Brent futures quotes around 14:15–14:25 London

