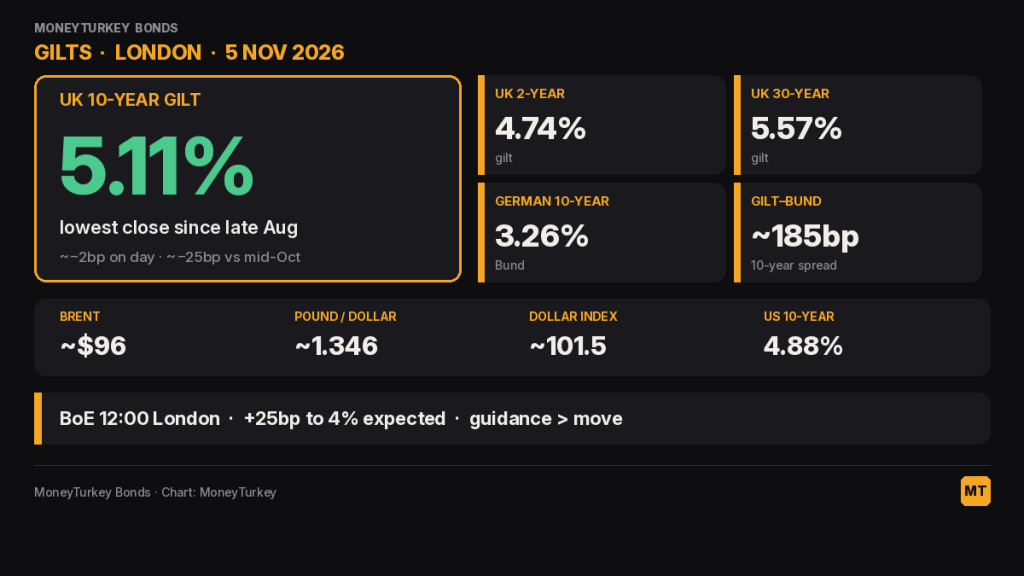
UK 10-year gilt yields slipped to 5.11%, their lowest close since late August, as the Bank of England heads into a widely expected hike to 4% at 12:00 London — with the oil slide doing more of the work for bond bulls than the central bank.
MoneyTurkey Bonds Desk | 5 November 2026, 11:20 London
Key points
- The 10-year gilt yield was 5.11% late morning in London, down about 2bp on the day and about 25bp below mid-October levels; the 2-year traded near 4.74%.
- Brent crude was near $96 a barrel, down from about $105 at the start of the week, easing the energy-led inflation that pushed UK CPI to 3.5%.
- Economists expect a 25bp rise in Bank Rate to 4%, the first hike since August 2023; the guidance, not the move, is what gilts are trading.
What happened
Gilts extended this week’s rally on Thursday morning. The 10-year yield fell to about 5.11% from a 5.14% close on Wednesday, according to CNBC market data, and the 30-year was near 5.57%. German 10-year Bund yields were about 3.26%, leaving the gilt–Bund spread near 185bp.
The move tracks crude. Brent futures traded around $96 a barrel after a sharp drop on Wednesday, cutting into the fuel and energy costs that lifted UK inflation above the Bank’s 2% target. Sterling still firmed to about $1.346, while the US dollar index held near 101.5.
US 10-year Treasury yields were about 4.88%, little changed, as investors digested the midterm results and waited for Friday’s October jobs report.
Why it matters
A hike that lands alongside falling long-end yields is a vote of confidence that the Bank will not need many more. If the Monetary Policy Committee signals one-and-done, the front end has room to rally further; a hawkish split or talk of a December follow-up would test the 2-year first. The Reuters economist poll cited in our BoE decision now shows an 8–1 vote for +25bp to 4% (Catherine L Mann preferred +50bp).
The same oil slide is moving markets the big outlets cover less: Indian government bonds rallied the most since April as oil slid, and the rupee firmed with them. For gilt investors, the risk is that a rebound in crude reverses the move faster than any MPC statement.
What to watch
- Whether gilt yields stay near session lows after the 8–1 hike and Bailey guidance
- Gilt 2-year reaction to any December signal
- Brent crude around $95–$100
- US October jobs report on Friday
Related on MoneyTurkey
- BoE Poised to Hike to 4% as Iran Oil Pushes UK Inflation to 3.5%
- Indian Bonds Rally Most Since April as Oil Slides After Midterm Sweep
- South Africa Debt Ratios Fall After GDP Rebase — Borrowing Unchanged
For information only. Not investment advice.
Sources
- CNBC market data: UK 2-, 10- and 30-year gilt, German 10-year Bund and US 10-year Treasury yields (5 November 2026, ~11:12 London); gilt 10-year daily closes since August
- Yahoo Finance: Brent crude futures, GBP/USD and US dollar index (5 November 2026, ~11:10 London)
- MoneyTurkey Economics Desk: BoE Poised to Hike to 4% as Iran Oil Pushes UK Inflation to 3.5% (UK CPI, Reuters poll)
- MarketWatch: Gilt Yields Drop to Multi-Week Lows Ahead of BOE Decision as Oil Prices Fall Back

