By MoneyTurkey editors | Andrew’s Corner | 6 November 2026, London
Yesterday I wrote that the blue wave had made America’s AI bill visible, and that the bill had landed in Seoul, Tokyo and Taipei first. Overnight the tape stopped debating the metaphor and issued a receipt.
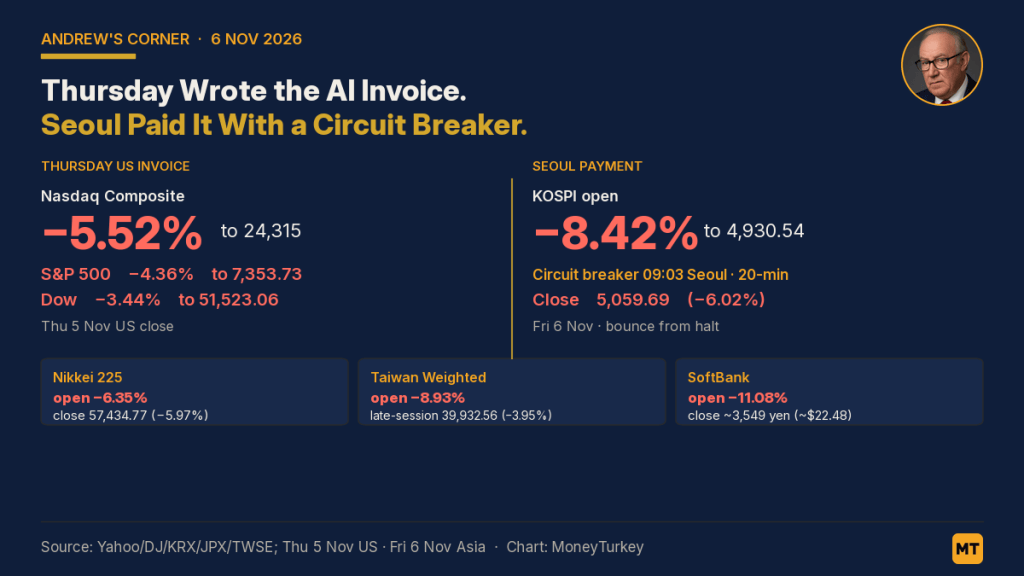
On Thursday the Nasdaq Composite fell 5.52% to 24,315.00 — a correction, and its worst day since April 2025. The S&P 500 lost 4.36% to 7,353.73. The Dow dropped 1,833.06 points, or 3.44%, to 51,523.06, erasing Wednesday’s post-midterm surge of 1,569 points to 53,356.12. The Philadelphia Semiconductor Index plunged about 12%; Nvidia fell roughly 9.26%; the Magnificent Seven shed more than $1 trillion of market value. That was Wall Street writing the invoice.
Friday’s Asia open was the first payment. The KOSPI opened down 8.42% at 4,930.54. At 09:03 Seoul time the Korea Exchange tripped its first-level circuit breaker and halted trading for twenty minutes; a sidecar followed at 09:34. Taiwan’s Weighted Index opened down 8.93% at 37,862.82. The Nikkei 225 opened down 6.35% at 57,197.55. Oceania stayed contained: the ASX 200 opened −0.70% at 9,001.30 and the NZX 50 −0.41% at 14,033.76.
The payment came before the legislature
Congress does not sit until January. State permitting fights take years. Federal AI bills can still meet a veto. None of that stopped the market from treating a slower AI buildout as priced.
That is the Day-two point. Yesterday’s Corner argued that New York had priced the saving for AI buyers and Asia had taken the hit for AI sellers. Thursday’s US session then repriced the sellers again, and Friday’s Asia open transmitted that second hit into a circuit-breaker print in Seoul before a single committee had gavelled in.
This is markets judgment, not a politics wrap. The midterms frame still earns the column because the tape is still pricing the Democratic sweep as a slower American AI buildout. The evidence today is not a speech. It is a halt.
The open was the signal. The close was the bounce.
Do not confuse the two. By the Asia session close the KOSPI had recovered to 5,059.69, down 6.02% versus Thursday’s 5,383.80. That is still below the 5,200 level I flagged yesterday as the Daishin watch line. The Nikkei closed 57,434.77, down 5.97% versus 61,077.90. The ASX 200 closed 9,007.5, down 0.64% versus Thursday’s desk lock of 9,065.1 — Oceania never joined the panic. Taiwan’s late-session lock on our desk stood at 39,932.56, down 3.95%, well off the open’s −8.93%.
A market that opens through a circuit breaker and closes with a partial reclaim is not calm. It is a market that showed you its worst print first, then spent the session negotiating how much of the invoice stays unpaid into the US open.
Who paid hardest
The early movers told the same hardware story as Thursday, only louder. SK Hynix fell 11.23%. SoftBank Group fell 11.08% at the open and closed near 3,549 yen (~$22.48). TSMC −9.60%. Samsung Electronics −8.73%. Advantest −11.33%. Tokyo Electron −8.59%.
SoftBank had a second bruise: China’s foreign-investment security review office prohibited SoftBank from acquiring ABB’s robotics business in China, in a notice dated 4 November that SoftBank and ABB both confirmed. The wider roughly $5.375 billion deal is still in dialogue. That is a separate China-risk line, not the AI-invoice thesis — but it helps explain why SoftBank’s tape looked uglier than a pure chip beta.
The yen did what havens do on a risk-off Asia morning. USD/JPY traded near 157.85, with the yen at a one-week high near 157.40.
My read
Yesterday I said a sidecar-day KOSPI with foreigners still buying futures was a market waiting to see the bill itemised. Overnight Wall Street itemised it. This morning Seoul paid the first instalment with a twenty-minute halt.
My read: the AI-invoice trade is no longer only a cross-Pacific rotation story. It is a global valuation reset of the sellers, and Asia’s hardware complex is still where the bill prints first and largest. Congress has not sat. The oil leg from yesterday remains unsettled. What settled overnight is that the market will not wait for January to collect.
What I’m watching: whether the KOSPI can reclaim and hold 5,200 after closing 5,059.69; whether Taiwan’s late-session reclaim toward 39,900 holds into the next session; SoftBank into the US open after the ABB China prohibition; and whether Friday’s US cash open treats Thursday’s Nasdaq correction as finished business or as a first draft.
Thursday wrote the AI invoice. Seoul paid it with a circuit breaker. The rest of the bill is still coming due.
For information only. Not investment advice. FX conversions at about ₩1,355 and ¥157.9 per dollar.
Sources
AP, CNBC, Fox Business: US closes — Nasdaq/S&P/Dow, SOX, Nvidia, Mag7 market-cap loss (5 Nov 2026)
Yonhap / JoongAng: KOSPI open, first-level circuit breaker 09:03 Seoul, sidecar 09:34 (6 Nov 2026)
Yahoo Finance via MoneyTurkey desks: Asia session closes — KOSPI, Nikkei (6 Nov 2026, ~08:10 London)
MoneyTurkey desks: Asia open / KOSPI halt, Oceania close + Taiwan late-session, SoftBank–ABB China block, Yen haven / USD/JPY
Yesterday’s Corner: The Blue Wave Cut America’s AI Bill. Asia Got the Invoice.

