The US Treasury market is shut on Wednesday for Veterans Day, leaving European bonds to absorb the aftermath of Tuesday’s inflation shock. German Bund yields held near 3.3% and the 10-year gilt stayed above 5.2%.
MoneyTurkey Bonds Desk | 11 November 2026
Key points
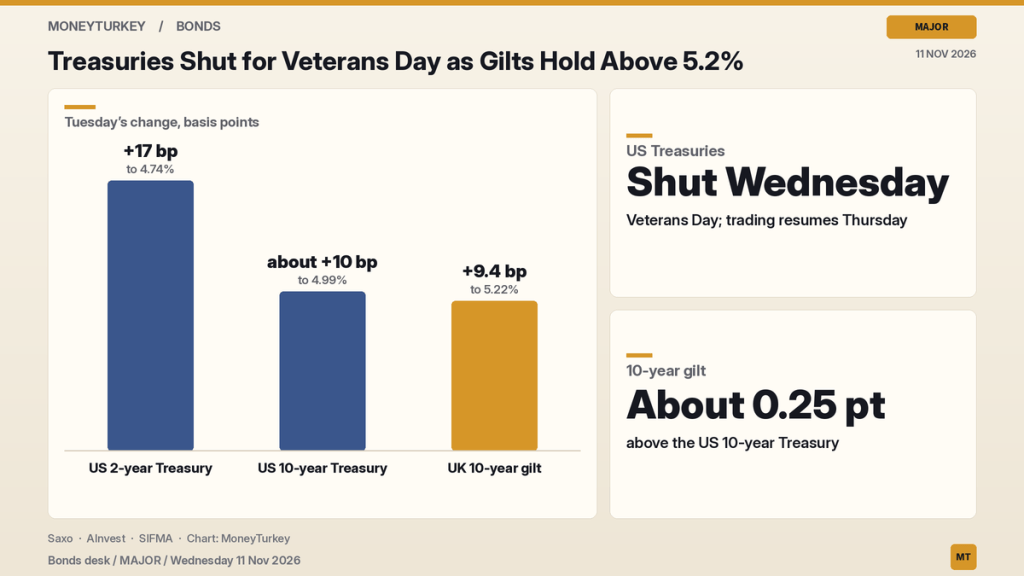
- SIFMA, the US bond industry group, recommended a full close of US dollar fixed income trading on Wednesday for Veterans Day. Bonds reopen on Thursday, while US stocks trade as normal.
- The US 2-year Treasury yield jumped about 17 basis points to near 4.74% on Tuesday and the 10-year rose about 10 basis points to near 4.99%, after briefly topping 5%.
- Germany’s 10-year Bund yield held around 3.3% on Wednesday.
- The UK 10-year gilt yield rose 9.4 basis points to 5.22% on Tuesday, about a quarter point above the US 10-year.
What happened
SIFMA confirmed on Oct. 28 its recommendation for a full market close on Nov. 11 for trading in US dollar government, corporate, municipal and mortgage bonds in the US, UK and Japan. Trading resumes on Thursday, Nov. 12, USA Today reported. Stock exchanges stay open.
The closure follows one of the sharpest Treasury sell-offs in weeks. US consumer prices rose 0.4% in October against 0.3% expected, and core prices rose 0.3% against 0.2%, according to Saxo and MNC Sekuritas. The 2-year yield climbed about 17 basis points to near 4.74% and the 10-year about 10 basis points to near 4.99%, after briefly trading above 5%, both reported. Weak demand at Tuesday’s 10-year note auction added to the pressure.
With New York shut, European markets traded thinly. The German 10-year yield held around 3.3% on Wednesday, according to Investing.com, with Trading Economics also putting the 10-year steady around 3.3%.
Why gilts stand out
British bonds took the heaviest hit in Europe on Tuesday. The 10-year gilt yield rose 9.4 basis points to 5.22% and the 2-year rose about 13 basis points to near 4.9%, according to AInvest, MNC Sekuritas and XMTrading. That leaves the 10-year gilt about a quarter point above the 10-year Treasury.
AInvest noted that the 10-year gilt reached about 5.25% in early September, its highest since the 2008 financial crisis, so Tuesday’s move takes it back close to that peak.
Why markets care
Rate-setters on both sides of the Atlantic are leaning toward more hikes. Fed Governor Christopher Waller backed a December increase and said a half-point move could be considered, while markets now fully price a December Fed hike, Saxo and Investing.com reported. European Central Bank chief economist Philip Lane said on Tuesday it would be “prudent indeed to hike” in December if the outlook was unchanged, according to Reuters and Econostream.
The Veterans Day pause means the Treasury market itself cannot react to anything said today until trading resumes on Thursday.
What to watch
- Whether the 10-year Treasury yield holds near 5% when trading resumes on Thursday
- Whether the 10-year gilt challenges its September high near 5.25%
- More ECB and Fed comments on December hikes
- Demand at the next US debt auctions after Tuesday’s weak 10-year sale
Related on MoneyTurkey
- Fed’s Waller Backs December Hike, Open to Half Point
- US October Deficit Hits $409 Billion as Yields Climb
For information only. Not investment advice.
Sources
- SIFMA: https://www.sifma.org/news/press-releases/sifma-fixed-income-market-close-recommendation-in-the-u-s-the-u-k-and-japan-for-the-u-s-veterans-day-holiday-2026
- USA Today: https://www.usatoday.com/story/money/markets/2026/11/10/stock-market-open-closed-veterans-day-2026/92704232007/
- Saxo: https://www.home.saxo/en-ch/content/articles/macro/market-quick-take—us-treasury-yields-rip-higher—11-november-2026-11112026
- MNC Sekuritas: https://www.mncsekuritas.id/risetdetail/mncs-fixed-income-report-november-11-2026/
- Investing.com: https://www.investing.com/news/forex-news/global-bonds-fall-as-hot-us-cpi-and-fed-rhetoric-stoke-fears-of-50bps-hike-5018037
- Trading Economics: https://tradingeconomics.com/germany/government-bond-yield/news/600366
- AInvest: https://www.ainvest.com/news/uk-gilts-dragged-bond-selloff-2611/
- XMTrading: https://fxplus.xmtrading.com/market-report/dzh261111070.html
- Reuters via Investing.com: https://www.investing.com/news/economy-news/ecb-may-need-to-hike-in-dec-chief-economist-says-5014403
- Econostream: https://www.econostream-media.com/news/2026-11-10/ecb%E2%80%99s_lane_says_december_hike_would_be_prudent_if_outlook_is_unchanged.html

