November loadings fall after summer shipments cut inventories, traders say.
MoneyTurkey Commodities Desk | 5 November 2026
Key points
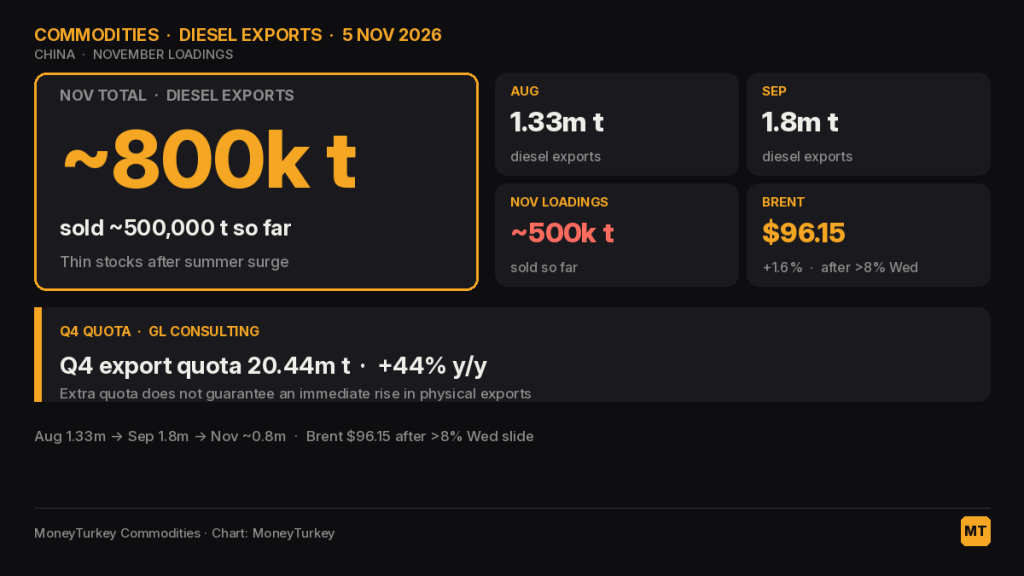
- Chinese refiners have sold about 500,000 metric tons of diesel for November loading, with total shipments expected to reach about 800,000 tons, down from 1.33 million tons in August and 1.8 million tons in September.
- China expanded the fourth-quarter refined-product export quota to 20.44 million tons, up 44% from a year earlier, but analysts note that additional quota does not guarantee an immediate rise in physical exports.
China’s diesel exports are on track to fall in November after heavy summer shipments reduced domestic inventories, according to traders and executives with knowledge of this month’s export plans. Refiners have sold about 500,000 metric tons for November loading so far, with total shipments expected to reach about 800,000 tons. That compares with 1.33 million tons in August and 1.8 million tons in September. The pullback follows a policy shift that first restricted exports between April and July, then allowed a rebound after mid-July when Beijing lifted those curbs.
What happened
Chinese refiners sold roughly 500,000 metric tons of diesel for November loading, with early estimates pointing to total November shipments of about 800,000 tons, traders and executives told Reuters, as reported by OilPrice. That volume is down sharply from 1.33 million tons in August and 1.8 million tons in September. October exports also eased after a week-long holiday pause before resuming around October 9.
China’s fuel export policies have shifted month to month since the Middle East crisis tightened crude and fuel supply earlier this year. Authorities and refiners prioritized domestic supplies, restricting exports from April through July. Exports recovered in August after Beijing removed the curbs, with total petroleum-product shipments reaching 6.01 million tons, up 12.7% from a year earlier. Jet fuel exports hit an all-time high that month, and overseas shipments stayed strong in September before the October slowdown.
Last week China expanded the fourth-quarter refined-product export quota to 20.44 million tons, up 44% from a year earlier, according to GL Consulting. Analysts at the firm said the additional quota headroom does not guarantee an immediate increase in physical exports, and the November plan remains under adjustment.
What is driving prices
The drop in planned diesel exports stems from thin domestic inventories after the summer surge in overseas shipments. Refiners and traders say the priority remains supplying the home market, which limits the volumes available for export. The policy environment has also played a role: export restrictions were in place during the peak of supply concerns, then lifted in mid-July, allowing the August-September rebound before the current pullback.
The expanded fourth-quarter quota gives refiners more room to ship product, but analysts note that quota allocations do not automatically translate into higher physical flows. GL Consulting said the November export plan was already expected to decline month on month before the latest quota increase, and any upward revision is still under review.
Why it matters
Lower Chinese diesel exports tighten available supply in regional markets that have relied on those barrels in recent months. Traders tracking arbitrage flows will watch whether the reduced November loadings push buyers toward alternative sources or prompt inventory draws elsewhere in Asia. The quota increase offers a potential offset, but the speed and size of any rebound in physical exports remain unclear.
The cut lands on a choppy crude tape. Brent futures were up about 1.6% at roughly $96.15 a barrel on Thursday, a partial rebound after both benchmarks fell more than 8% on Wednesday to their lowest settlement since August 31. Lower crude does not ease product tightness in Asia if Chinese refiners keep diesel at home, so the gap between crude and middle-distillate supply is what traders will watch.
For diesel crack spreads and regional arbitrage, the key variable is how quickly Chinese refiners can rebuild stocks while meeting domestic demand. If inventories stay thin, export volumes could stay capped even with higher quotas, keeping the market tighter than headline quota numbers suggest.
What to watch
- November diesel loading data and any late-month deals
- GL Consulting updates on quota-driven export revisions
- Regional diesel inventory reports in key import markets
- Refinery maintenance schedules that could affect domestic supply
Related on MoneyTurkey
- Gold Rallies as Dollar and Yields Soften After US Midterms
- India Approves $297 Million Subsidy for Lithium and Nickel Refining
For information only. Not investment advice.

