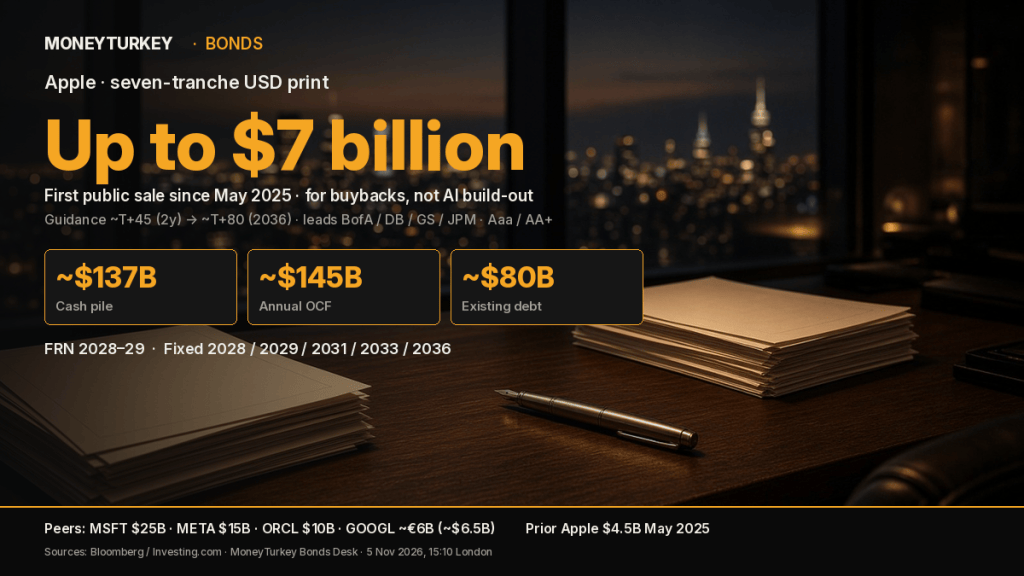
Apple is marketing up to $7 billion of seven-tranche dollar bonds, its first public sale since May 2025, as Big Tech’s high-grade calendar stays crowded and the company borrows for buybacks rather than AI build-out.
MoneyTurkey Bonds Desk | 5 November 2026, 15:10 London
Key points
- Apple is seeking up to $7 billion across floating notes due 2028–2029 and fixed notes due 2028, 2029, 2031, 2033 and 2036.
- Fixed-rate guidance is about 45 basis points over Treasuries for the two-year tranche and 80 basis points for the 2036 notes; floating paper is marketed over SOFR.
- Bank of America, Deutsche Bank, Goldman Sachs and JPMorgan lead; expected ratings Aaa (Moody’s) / AA+ (S&P).
- The sale sits in a Big Tech wave — Microsoft $25 billion last week, Meta $15 billion, Oracle $10 billion, Alphabet about €6 billion (roughly $6.5 billion) — but Bloomberg Intelligence calls Apple’s print opportunistic given roughly $137 billion cash and $145 billion annual operating cash flow.
What happened
Apple filed the deal on Thursday, 5 November, with pricing expected the same day. Proceeds are earmarked for general corporate purposes, including share repurchases, dividends, working capital, capital expenditure, acquisitions and debt repayment. The last comparable sale was a $4.5 billion offering in May 2025; a full $7 billion print would be about 56% larger.
The mix of fixed and floating paper tests demand across the front and intermediate curve. Guidance widens with maturity, from about 45 basis points over Treasuries for the 2028 fixed notes to 80 basis points for 2036. Existing Apple debt is about $80 billion.
What is moving credit
For bond desks, the story is less funding stress than supply. Hyperscalers have been borrowing for AI infrastructure; Apple’s cash pile and lighter AI capex profile let it tap the market for capital returns without the same credit-stretch narrative. That distinction matters for relative-value books comparing Apple spreads with Microsoft, Meta and Oracle paper after this week’s prints.
A modest new-issue concession would show the high-grade bid can still absorb large tech supply after midterms week. Stretching on the 2036 tranche, or soft books in floating notes, would flag fatigue after the Microsoft and Meta deals.
Why it matters
Aa+/Aaa tech benchmarks reset how desks price the rest of the high-grade calendar, including sovereign and EM names MoneyTurkey has been tracking — from South Africa’s debt-ratio rebase to India’s oil-led bond rally. A clean Apple print keeps the path open for other issuers; a stumble would widen the gap between cash-rich US tech and higher-beta credits.
What to watch
- Final pricing versus guidance and order-book coverage by tranche
- Secondary moves in existing Apple bonds and peer Big Tech credits
- Whether the 2036 tranche needs a wider concession than the front end
- Follow-on high-grade tech supply into year-end
Related on MoneyTurkey
- Gilt Yields Hit Lowest Since August Ahead of BoE Hike
- South Africa Debt Ratios Fall After GDP Rebase — Borrowing Unchanged
- Indian Bonds Rally Most Since April as Oil Slides After Midterm Sweep
For information only. Not investment advice.
Sources
- Deal terms reported via Bloomberg / Investing.com market wrap, 5 November 2026: Yahoo Finance syndication
- Bloomberg: Apple kicks off high-grade debt sale

