Guinea wants to become West Africa’s gold refining hub. For now, its biggest miners are holding bullion they are not allowed to export, while the country’s new refinery is only just starting work.
MoneyTurkey Commodities Desk | 17 November 2026
Key points
- Miners including AngloGold Ashanti, Nordgold and PDI Gold have built up gold inventories worth tens of millions of dollars that they cannot export unrefined, Reuters and Mining Weekly reported, citing three mining executives and two lawyers
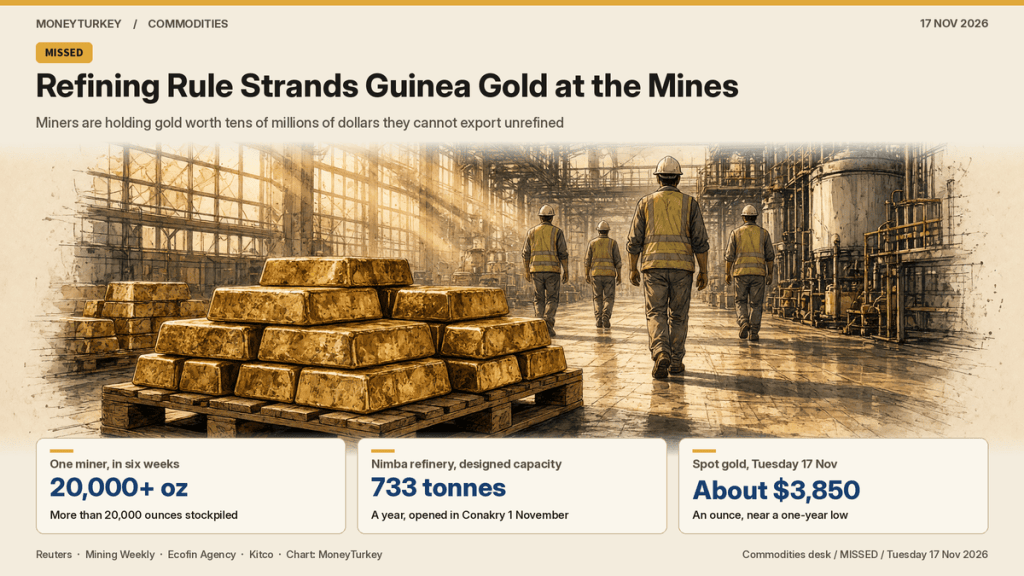
- One producer has stockpiled more than 20,000 ounces in six weeks and doubled its insurance cover, an executive told Reuters; at about $3,850 an ounce that is roughly $77 million, by MoneyTurkey’s calculation
- The 90-day window to export unrefined gold closed on 6 October, and the Nimba Gold Refinery in Conakry opened on 1 November, according to Reuters and Ecofin Agency
What happened
Guinea’s government now requires gold to be refined in the country before it leaves. Producers were given a 90-day transition to keep shipping unrefined metal to overseas refiners, and that window ended on 6 October, Reuters and Ecofin Agency reported. Since then, bureaucracy and a slow start to domestic refining have left miners with metal piling up, the industry sources told Reuters. One executive said producers had been accumulating gold for more than four weeks.
Mines Minister Bouna Sylla told Reuters that the Nimba refinery has begun processing gold and that a major refiner based in the United Arab Emirates has been appointed to run it, though he declined to name the company. He said the government is discussing commercial arrangements with the miners. PDI Gold told Reuters it supports Guinea’s push to keep more value from its natural resources at home.
The bigger plan
The Nimba plant is designed to process up to 733 tonnes of gold a year, Ecofin Agency and MiningFeeds reported. Business Insider Africa described the rules as part of a wider drive to keep more of Guinea’s mineral wealth at home.
There was one sign of movement on Tuesday. PDI Gold received its long-awaited exploitation permit for the $463 million Bankan project, Reuters and Mining.com reported, after a wait of nearly two years. Chief executive Matthew Wilcox told Reuters construction would probably start within four to six weeks. Executives have complained that permits in Guinea have been stalled for more than two years.
Why it matters
Gold sitting in a vault in Conakry earns nothing and costs money to insure, so the hold-up ties up working capital for the miners. It comes as the metal is already weak: spot gold traded near $3,850 an ounce on Tuesday, close to its lowest level in more than a year, according to Kitco and CNBC. Kitco tied the pressure to expectations that the Federal Reserve will raise interest rates again in December. A stockpile in Guinea does not mean the world is short of gold, but it shows how quickly a resource nationalism push can turn mined metal into metal that cannot be sold.
What to watch
- Whether the Nimba refinery names its UAE operator and clears the backlog of stockpiled gold
- Any commercial deal between the government and AngloGold Ashanti, Nordgold or PDI Gold
- Details of the central bank’s plan to buy up to 30% of industrial output
Related on MoneyTurkey
- Copper Cheapens in London as Shanghai Runs Short of Metal
- Aluminium Squeeze Deepens as LME Shorts Hit Roll Deadline
- Musalem Maps More Hikes Than Markets Have Priced
For information only. Not investment advice.
Sources
- Reuters via MarketScreener: Guinea’s miners stockpile gold after refinery rules halted exports, sources say
- Mining Weekly: Guinea’s miners stockpile gold after refinery rules halted exports
- Business Insider Africa: Guinea’s push to retain more gold wealth at home is disrupting exports
- Ecofin Agency: Guinea opens its first gold refinery
- Mining.com (Reuters): Guinea clears PDI Gold permit
- Kitco: Gold trades near one-year low as US retail sales slow
- CNBC: The price of gold today, 17 November 2026

