Short sellers in London aluminium hit their roll deadline as spot metal trades far above the benchmark. Almost all the remaining stock is Russian metal many buyers avoid.
MoneyTurkey Commodities Desk | 17 November 2026
Key points
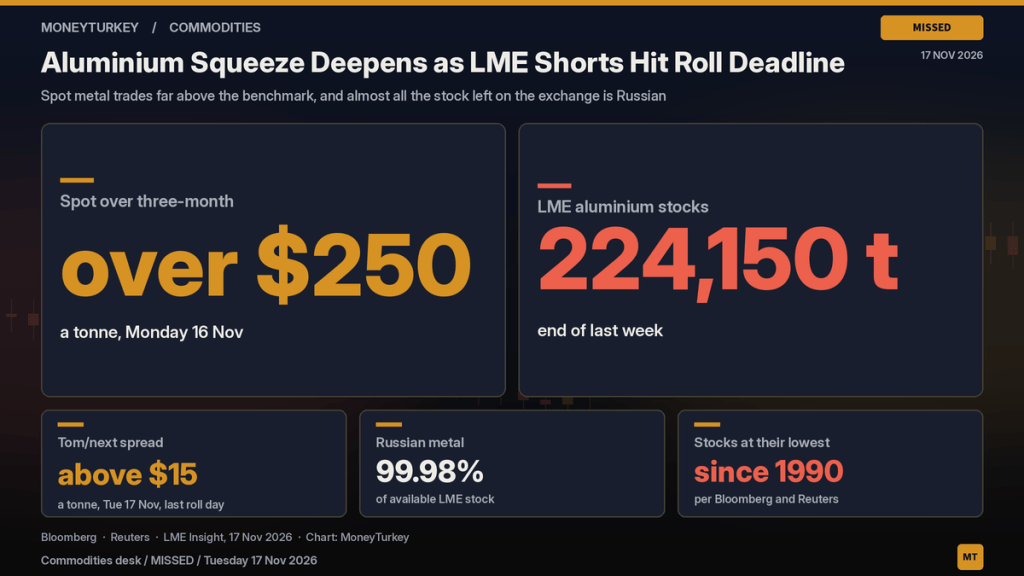
- The tom/next spread on the London Metal Exchange, the cost of rolling a position forward by one day, rose above US$15 a tonne on Tuesday, the last day to roll short November positions, according to Bloomberg and FX168
- Spot aluminium traded more than US$250 a tonne above the three-month contract on Monday, according to Bloomberg and ING; a Reuters column put the premium at US$275
- LME aluminium stocks are at their lowest since 1990, according to Bloomberg and Reuters
- Nearly all the metal still available on the exchange is Russian, which the US bans and many buyers shun, according to Reuters and LME Insight
The squeeze on London aluminium tightened again on Tuesday. With traders holding short November positions out of time to roll them, the one-day tom/next spread jumped above US$15 a tonne, according to Bloomberg and FX168. A day earlier, spot metal changed hands at more than US$250 a tonne over the three-month contract, Bloomberg and ING reported. Reuters columnist Andy Home put Monday’s premium at US$275, a degree of tightness not seen since the squeezes of 1988 and 1990.
The stock that is left
LME aluminium inventories are at their lowest since 1990, according to Bloomberg and Reuters. Total stocks ended last week at 224,150 tonnes, LME Insight and Streamline Feed reported.
The part the headlines miss is what that stock is. At the end of October, all but 50 tonnes of the metal on warrant was Russian-brand aluminium made before US and UK sanctions in April 2024, Reuters reported; LME Insight put Russian metal at 99.98% of available stock. That metal is banned in the US, about to be banned in Europe and avoided by many Asian manufacturers, according to Reuters. So a buyer that will not take Russian aluminium has even less to draw on than the 1990 low suggests. Now some of that Russian metal is also being cancelled for physical delivery out of the warehouses, according to Reuters.
More supply, but not where it is needed
Nicholas Snowdon, head of metals and mining research at Mercuria Energy Group, told an industry conference in Shanghai on Tuesday that there is “building potential” for prompt spreads to see “further bouts of tightness”, and that the market will have “very limited inventory cover” over the next few weeks and months, according to Bloomberg.
He said global supply is set for its biggest year-on-year rise in three decades, with output expected to grow about 6% next year against demand growth of about 2%, according to Bloomberg and Streamline Feed. Much of that new metal will not at first be deliverable on the LME, which leaves exchange inventories open to more pinch points. ING said it expects the tightness to keep supporting prices in the near term, while stronger production should loosen the global balance next year.
Why it matters
A squeeze on the exchange is a cost problem for anyone short. Sellers who cannot deliver must buy back their positions or pay to roll them, and the thinner the usable stock, the more that costs.
What to watch
- Daily LME aluminium stock and cancelled-warrant reports
- The tom/next and spot-to-three-month spreads after the November roll
- Whether off-warrant metal in Rotterdam is moved onto warrant
- Any new LME-registered brands from the incoming supply
Related on MoneyTurkey
- EU Duties Land Lightest on Turkish Steel, Heaviest on Japan
- OPEC Audits Its Capacity as Guyana Tops 1 Million Barrels
- Gold Falls to Lowest Since October 2025 Before Fed Minutes
For information only. Not investment advice.
Sources
- Bloomberg: Aluminum squeeze intensifies with traders scrambling for metal (also via The Edge Malaysia)
- FX168: LME aluminium tom/next above US$15
- ING THINK: The Commodities Feed: Metals under pressure while oil supply improves
- Reuters (Andy Home), via MINING.COM: Crunch time for aluminum as buyers tap metal of last resort
- LME Insight: The LME Weekly Review: 9-13 November 2026
- Streamline Feed: Aluminum squeeze sends London spot premium past $250

